Diamond Industry Navigates Uneven Recovery and Evolving Trends in 2026
The diamond industry is charting a course through a complex 2026, characterized by an uneven global recovery, evolving consumer preferences, and the increasing impact of technology and policy. Senior diamantaires and industry analysts in India highlight key trends that businesses must monitor to navigate the year ahead.
Uneven Recovery and Shifting Demand
While overall demand for diamonds showed positive signals in markets like the United States and India in 2025, the recovery is far from uniform. China remains an exception, though demand may have bottomed out. The luxury segment, particularly diamonds larger than 2 to 3 carats, is performing strongly, with prices firming up. Smaller diamonds (below 0.18 carats) are also seeing price improvements, signaling a move towards stability. However, the mid-tier market (20 points to 2 carats) remains stressed. This is attributed to subdued demand from China and a significant market share captured by synthetic diamonds in the U.S.
Russell Mehta, managing director of Rosy Blue India, noted, “Demand for larger goods (above 2 to 3 carats) is fairly stable and prices have begun to firm up.” He added, “Prices have improved but continue to be soft, signs that stability is on the horizon,” for smaller goods. However, he described the mid-tier segment as “stressed and difficult”.
Trade Policies and Supply Dynamics
Tariffs, sanctions, and trade deals continue to shape the industry. While concerns over Russian diamonds have receded, trade negotiations, particularly between India and the U.S., have been pivotal. An earlier expectation of tariff exemptions for natural diamonds and gemstones was short-lived, with tariffs hovering around 10-15 percent. Despite these complexities, India's trade deals with the UK, EU, Oman, and Australia are expected to provide smaller boosts.
Supply-side equilibrium is anticipated by mid-2026, driven by tighter supply rather than surging demand. Global rough production has decreased significantly from its peak, with major mining companies reducing guidance and smaller mines undergoing maintenance or closure. The midstream sector has also restructured, with overall capacity well below post-COVID peaks. Industry analyst Pranay Narvekar expects a semblance of equilibrium to return, noting, “Rough production for the market is now way below the peaks of the past,” predicting it will hover around 100 million carats for the next few years.
Marketing Push and Government Involvement
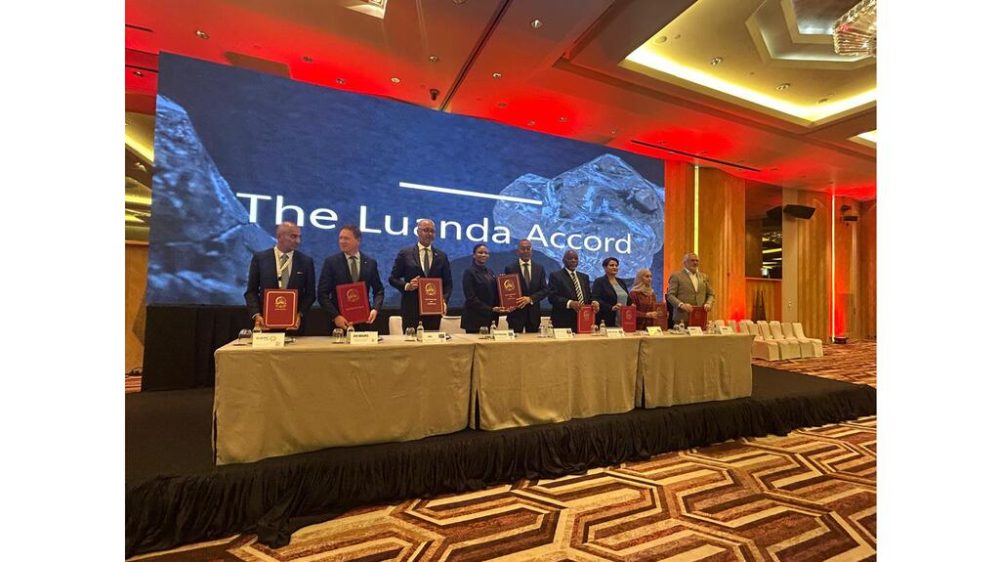
A significant marketing push for natural diamonds is imminent, fueled by the Luanda Accord signed in June 2025. This agreement sees diamond-producing countries and industry organizations commit funds to the Natural Diamond Council for marketing. Shaunak Parikh, vice chairman of India’s Gem & Jewellery Export Promotion Council (GJEPC), stated, “The Luanda Accord on generic marketing was an important turning point for the industry.” This initiative aims to launch a global promotional campaign in key markets during peak selling seasons.
Governments are playing an increasingly significant role. Beyond marketing, there's a possibility of diamond mining countries becoming new majority stakeholders in De Beers, as Anglo American seeks to offload its stake. Discussions are in advanced stages with several interested parties, including government consortiums. India's leadership of the Kimberley Process this year also aims to revitalize its chain of custody mechanism, with initiatives like the C-3 plan focused on boosting consumer confidence, credibility, and compliance.
The Rise of Lab-Grown Diamonds and AI
The rapid growth of lab-grown diamonds may be reaching its peak, with wholesale prices declining drastically. While unit sales continued to grow due to increased volume, this trend is leveling out. Retailers are pressured to sell larger volumes to maintain profits. Data analytics firm Tenoris reports a decline in loose lab-grown diamond unit sales in January, suggesting a transition to a more mature market phase.
Artificial intelligence is making a notable impact, particularly in the business planning and trading layers of the loose diamond segment. AI-driven pricing intelligence, inventory optimization, and demand/supply analytics are in daily use. Generative AI is also expected to influence product development, manufacturing, and consumer marketing in the jewelry sector.
Consumer Preferences and Geographic Influences
Consumers are increasingly prioritizing sustainability and transparency, with demands for blockchain-verified origins and recycled metals. Lab-grown diamonds now account for over 50% of engagement ring purchases due to their significantly lower cost, enabling buyers to prioritize size and quality. However, diamond preferences vary significantly by geographic location. New York buyers favor larger engagement rings (1.0-1.1 carats) compared to London buyers (0.6 carats). Chinese buyers often demand top color and clarity grades (D-F, VVS+), while American buyers may trade off color and clarity for larger carat weights.
“Superior cut quality outlasts every trend cycle,” emphasizing the enduring importance of well-proportioned diamonds. Round brilliant cuts remain dominant, accounting for approximately 75% of all diamonds sold, due to their proven light performance. Social media continues to influence trends, making them more volatile but also more democratic, with user-generated content and celebrity endorsements shaping demand.
Sources
- —
- —